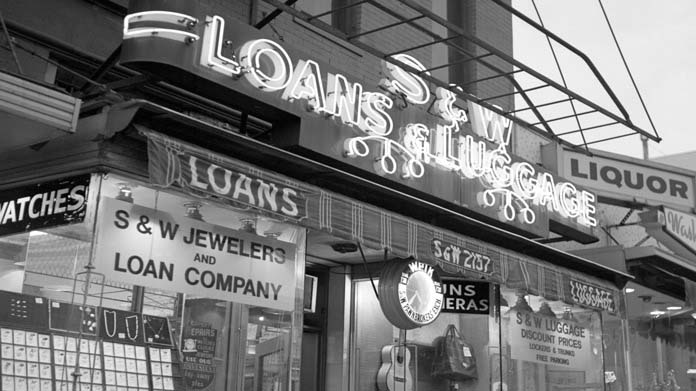
Part 1 - How to Start a Pawn Shop - Background
A pawn shop makes collateral-secured loans and may also buy and sell secondhand goods. This guide selects a pawnbroker, not an ordinary used-goods retailer or unsecured lender. Principal advanced to a customer, collected loan charges and merchandise sales have different accounting and cash effects.
Evaluate actual lawful products, local customer needs, competent appraisal/security and complete funding and operating costs before committing. Neither high monthly charges nor collateral alone establishes a profitable or compliant business.
Our guide is in 3 parts:
- Part 1 - How to start a Pawn Shop business - Background
- Part 2 - Our planner tool to see if this idea is the right fit for you
- Part 3 - Action plan to get started
Industry Overview
Use dated primary evidence with its actual scope. FirstCash’s 2025 filing reports U.S. pawn-segment retail merchandise sales of about $1.0463 billion and pawn loan fees of $555.0 million, and a 42% gross margin on those retail sales. This is one large operator’s segment, not independent-store averages, national revenue shares, net profit or recommended rates.
The old national store/revenue totals, 2018–2028 growth figures and online-penetration percentages were not substantiated. Validate actual lawful local lending and resale demand, competition, merchandise liquidity, loan redemptions and complete collected contribution. Online operations can add licensing, identity, data, fulfillment and consumer obligations.
Startup Costs
Separate funds committed to loan principal and inventory assets from startup expenses, recurring work and liquidity reserve. Quote the actual premises, secure pledged-property storage, appraisal/testing equipment and qualified training, records/loan systems, insurance, professional support, permissions and opening promotion. Plan all owner/staff work and lawful loaded coverage; no national minimum loan fund, fixed gemologist headcount or complete startup range was verified.
Build a cash forecast for new advances, redemptions, lawful collected fees, holding/forfeiture/sale timing, slow inventory, funding repayments and claims. Loan principal outflow is not simply an operating expense, and its repayment is not fee income; use suitable accounting review.
One local example is NYC’s current checklist: it requires a $10,000 surety bond and lists separate fingerprinting and license charges. The bond’s face amount is not its premium. The ordinary May–October application fee is $500 for an annual term; date-dependent shorter/combined options differ. Buying/selling secondhand articles also requires the listed secondhand-dealer license, and state registration is additional.
Budget ongoing owner/staff appraisal, customer/records work, premises, security, insurance, systems, legal/accounting, funding cost, inventory loss/markdowns, tax and administration. Investigate actual collateral ownership, identity, reporting, holding/sale, surplus, consumer credit/disclosure, military, privacy/data, applicable AML and product-specific obligations. Firearms and other regulated goods require separate authority and competence; a general pawnbroker license is not blanket permission.
Earning Potential
Possible income includes legally earned loan charges and lawful merchandise sales; repayment of principal restores the loan asset rather than creating fee income. Direct purchases and forfeited collateral can generate retail gross profit after their cost, but lawful holding, sale, notice and surplus duties must be satisfied. For example, New York’s section 50 requires specified surplus after deductions to be paid to the person entitled to redeem the pledge. Do not assume all proceeds belong to the operator.
Set actual products and total customer cost only after jurisdiction and borrower protections are assessed. New York’s section 46 caps collateral-loan interest at 4% per month or fraction, with other statutory provisions; it is a local example, not a nationwide rate. CFPB’s MLA guidance explains the 36% Military Annual Percentage Rate ceiling for covered credit/borrowers, including certain fees and additional restrictions. MAPR is not interchangeable with a monthly interest quote or permission to charge that amount.
The old $86,000 calculation on $100,000 lent represents an assumed annual funding spread at continuous fully performing balances before staff, premises, security, appraisal, compliance, inventory/claim losses, tax and other costs. It is not profit or evidence that the assumed 8%–12% monthly charges are lawful. No universal 80% loan-fee revenue mix, 25% default rate, 8% net margin or 18–36-month investment recovery was established.
Measure collected lawful loan fees plus retail sales less merchandise cost, then subtract complete operating and funding costs without counting principal or stock cost twice. Build break-even from the actual mix, legally permitted terms, collection and redemption/forfeiture timing, owner compensation and capacity. A positive accounting month differs from enough cash to fund the next advances and return an owner’s investment.
How to Start a Pawn Shop FAQs
How profitable is a pawn shop?
There is no verified profit amount per $100,000 lent. Loan principal, lawful collected charges, merchandise gross profit, complete operating costs, funding cost and tax must be distinguished. The earlier $86,000 figure omitted major expenses and legal/collection constraints.
Assess an actual loan/retail cash forecast and operating statement with qualified review; a large chain’s retail gross margin is not an independent owner’s net return.
How do pawn shops make most of their money?
A pawnbroker may earn lawful loan charges and retail contribution from directly purchased or properly forfeited merchandise. Actual mix varies; no representative 80% interest share was established.
Keep loan principal separate from fee revenue and cost merchandise and any required surplus disposition correctly. Retail sales totals are not retail gross profit or whole-business net earnings.
What are the rules of a pawn shop?
Identify the actual state/local licenses, identity and ownership checks, pawn-ticket disclosures, rate/fee limits, records/reporting, holding/redemption, notice/sale and surplus requirements. Federal consumer-credit, military, privacy/security and other applicable rules also need competent review; product categories can add separate permissions.
Reporting frequency and exact terms vary. The NYC/New York examples above are not a nationwide checklist or professional approval, and operating online does not remove duties.
Is it cheaper to pawn or sell?
Compare the actual cash offered, total lawful redemption cost including applicable charges, timing, alternatives and the risk of losing the item. A loan preserves a chance to redeem under its terms; an outright sale transfers ownership and has a different economic effect.
Pawning is not universally cheaper, and costs are not necessarily interest alone. Give clear terms and avoid pressure or assurances that borrowing is affordable for a particular customer.
Part 2 - Is this business right for you?
Business Evaluation & Strategy Tool
We'll walk you through the four pillars every business needs: Points of Leverage, Marketing Strategy, Financial Model, and Personal Compatibility. At the end you'll see a personalized report and your action plan below will be tailored to your answers.
This guide's benchmarks are under editorial review. Enter your own figures and choose the assumptions that fit your business.
Step 1 of 4 — Points of Leverage
Every viable business has natural advantages. Below are common leverage points across four categories. Pick the ones that apply to your Pawn Shop business.
Step 2 of 4 — Marketing Strategy
Without a way to connect with customers, even great businesses fail. Pick the channels you plan to use to reach your customers.
Step 3 of 4 — Financial Model
Enter your monthly baseline costs — the minimum overhead to keep the business running. Then we'll estimate how many customer transactions would cover that overhead before variable costs.
Step 4 of 4 — Personal Compatibility
A business that doesn't fit your life will fail no matter how good the numbers look. Tell us how this business fits you.
Your Pawn Shop Evaluation Report
Complete the four pillars and your personalized summary will appear here.
Points of Leverage
Marketing Strategy
Financial Model
Personal Compatibility
Part 3 - Your business launch action plan
Before committing to launch costs, test your business idea with potential customers. Use the free worksheet to record the offer, evidence and next decision.
Nine concrete steps to take you from idea to open business, grouped into 30-day phases. Adjust the phases to fit your funding, permits, and operating needs. Complete the planner above and we'll highlight what's most important for your situation.
First 30 days — Foundation
-
Choose a permitted business structure
Compare structures permitted for your activity, location, ownership and tax situation. Professional practices can have special entity and ownership rules. Check those requirements before filing; an LLC does not protect against every kind of personal liability.
-
Check tax IDs and registrations
Determine whether you need an EIN based on ownership, tax treatment, employees and applicable tax obligations. Some sole-owner businesses do not need one for federal income-tax purposes, while a bank or state may still require it. Apply directly with the IRS when needed and check applicable state or local registrations.
-
Separate business finances
Choose an appropriate business account and keep clear financial records. Separating business and personal transactions supports bookkeeping and entity formalities. Banks have their own eligibility and documentation requirements; a separate account is not a guarantee against personal liability.
-
Set up business accounting
Recording expenses and income from day one makes tax filing easier and lets you see when the business is actually profitable. Use software (QuickBooks, Wave) or a part-time bookkeeper.
Days 30–60 — Compliance & Risk
-
Get permits and licenses
Check the authorities responsible for your business activity and operating location. Professional authorization, tax registration, facility permits and product requirements are different questions. Online or mobile operations can still have licensing and other regulatory obligations.
-
Get business insurance
Identify the risks and coverage obligations for your activities, workers and location. Review applicable liability, property, professional or product coverage and workers’ compensation with the relevant state authority and a licensed insurance professional. Required coverage varies by jurisdiction and operation.
Days 60–90 — Launch
-
Define your brand
Choose a name, message and visual identity that help your intended customers understand the business. Check relevant name and trademark requirements before investing in a brand; a logo or business-name registration alone does not establish complete legal protection.
-
Create your business website
Choose a web presence that fits how your customers research and buy. A website can explain your offer, support inquiries or sales, and connect your marketing channels. Plan the content, accessibility, privacy and maintenance requirements for the features you need.
-
Set up your business phone system
Choose a customer-contact setup that fits your sales and service process. Compare current provider terms, business-use eligibility, routing features and ongoing costs, and decide how you will keep personal contact details separate.